

Credit Card : Wallet & NFC
by Galaxy studio apps
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
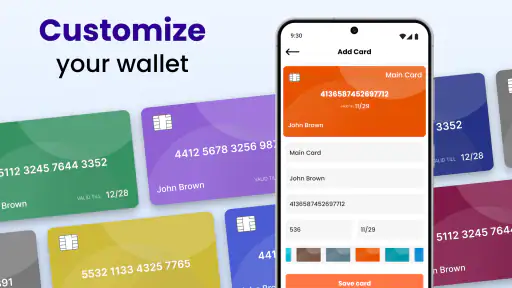
When I first opened Credit Card : Wallet & NFC, I expected another basic finance utility that simply stores card details. Its more interesting idea is the combination of a mobile wallet, an NFC scanner, and a credit or debit card BIN validator. That focus makes it useful for a very specific job: checking and organizing card information quickly, rather than replacing every function of a bank app or a full payment service.
I see it as a practical companion for people who handle several cards, need to identify a card network or issuer, or want to inspect the information encoded in a card’s first digits. The app is free to install, rated for Everyone, and developed by Galaxy studio apps. It has reached over five million installs and holds a 4.6 average from around sixty-eight thousand ratings, which suggests that its straightforward purpose has found a sizeable audience.
Why the BIN validator is the real focus
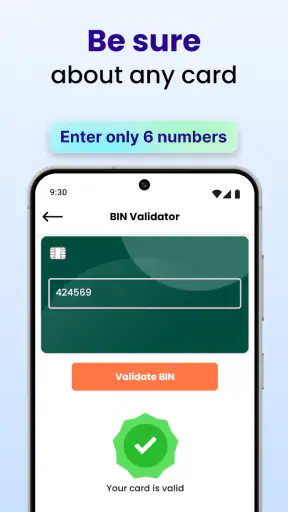
The most useful capability here is the BIN validator. BIN refers to the opening digits of a payment card number, traditionally used to identify information such as the issuing institution, card network, and card type. In everyday terms, the tool helps answer a question that is often awkward to investigate manually: what kind of card is this likely to be?
That can be handy when I am sorting cards in a wallet, checking whether a card belongs to the expected network, or reviewing payment information before entering it into another service. Instead of treating every card number as an anonymous string, the validator gives those opening digits a practical context. It is not the same as confirming whether a card has money available or whether a payment will be approved, but it can make card identification less confusing.
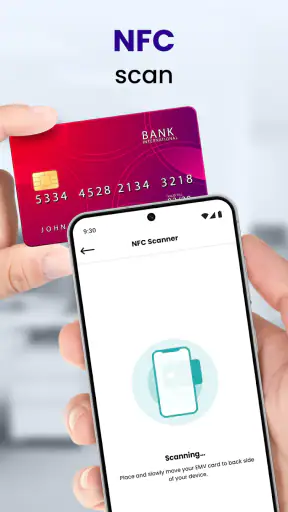
The NFC scanner adds a second route for working with card information. On a compatible phone, NFC can read information that a contactless card makes available to a nearby device. The important point is to think of this as a convenience for inspection, not as a guarantee that the phone can reproduce the complete function of a bank card. A scan may be useful for recognizing or organizing a card, while actual contactless payments still depend on the phone, bank, card issuer, and supported payment system.
The app is strongest when it reduces uncertainty around a card, not when it tries to become your bank. That distinction matters. A BIN result can help identify a card’s structure, but it should not be treated as proof that the card is active, genuine, funded, or safe to use. I would use the result as an informational check and still rely on the issuing bank for anything involving account status or security.
What using it feels like
The basic workflow is easy to understand. I would open the wallet area, choose the card-related tool, and either work with the card information already available or use the NFC scanner when the device and card support that interaction. The validator then focuses on the identifying portion of the card number rather than asking me to interpret the digits myself.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is more useful than it sounds when several cards look alike. A household may have a personal debit card, a shared credit card, an old replacement card, and a business card stored together. If the physical designs are similar, the first digits provide a quicker way to distinguish them than repeatedly opening a banking app and checking the full account name.
I also like the idea of using the scanner before typing card information into a form. It can serve as a small verification step: I can check that the card I picked is the one I intended to use before moving on. That does not eliminate the need to check the cardholder name, expiry information, or security code, but it can prevent a simple mix-up at the beginning of the process.
There is a useful trade-off between convenience and caution here. NFC is fast because it avoids manually entering some information, but I would not scan cards casually in public or leave them exposed on a desk. A finance app deserves the same care as a banking tool: use it in a private place, keep the phone protected, and avoid treating a quick scan as harmless just because it takes only a moment.
A realistic everyday scenario
Imagine that I am preparing for a trip and have three payment cards in front of me. One is the card I normally use, one is a backup debit card, and another belongs to a different account that I do not want to use for travel spending. The physical cards have similar colors, and I do not want to discover the mistake after adding one to a booking form.
I could use the wallet and BIN tools to identify the cards more quickly, then label or organize them according to their purpose. If the phone supports the necessary NFC interaction, scanning can reduce the amount of manual entry. The result is not a full travel-money system, but it is a sensible preparation step that helps me avoid choosing the wrong card.
Another scenario involves receiving a replacement card. Before putting the old card away for disposal, I can compare the identifying information of the replacement with the card I expected to receive. If something looks inconsistent, the right next step is contacting the bank, not assuming that the validator has proven fraud. The app helps with the first check; the issuer remains the authority.
For someone who sells products or manages small purchases, the validator may also help sort cards during routine reconciliation. It can make a pile of payment records easier to classify by card type or issuer. I would still avoid entering unnecessary full card numbers into any tool. The safest workflow is to use only the information needed for the task and keep sensitive details out of notes, screenshots, and shared devices.
Where it differs from ordinary alternatives
A bank’s official app is usually the better choice for balances, transactions, freezes, alerts, transfers, and account security. It knows the relationship between the card and the account, while a BIN validator mainly interprets identifying digits. If my goal is to manage money, I would open the bank app first.
A general mobile wallet is also better when the main task is paying in stores, using transit, or managing supported digital payment credentials. Those services are built around payment authorization and device security. Credit Card : Wallet & NFC is more appealing when I want a card-focused inspection tool alongside that everyday wallet, especially for identification and organization.
There is also a difference from simply searching the first digits online. A web search may produce scattered or outdated answers, while a dedicated validator presents the task in a more focused way. The convenience is valuable, but it does not remove the need for judgment. Issuer databases can change, card programs can be unusual, and a result may describe the general card range rather than the exact account in my hand.
In my view, the app fits between a card-notes utility and a payment companion. It is more specialized than a standard notes app, but less authoritative than a bank application. That middle position is its strength and its limitation at the same time.
Important trade-offs before relying on it
The first limitation is that a BIN result cannot answer every question a user may have. It may help identify the likely issuer or network, but it does not replace an authorization check. A card can be correctly identified and still be expired, blocked, over its limit, or unsuitable for a particular merchant.
The second issue is NFC compatibility. The presence of an NFC scanner does not mean every phone or every card will produce the same result. The phone must support NFC, and the card must expose information that the device can read in a useful way. I would treat scanning as an optional convenience rather than the only way to use the app.
Privacy is another practical consideration. Card numbers are sensitive, even when the tool is only interested in their opening digits. I would avoid scanning someone else’s card without permission, avoid saving more information than necessary, and be careful when using the app on a shared phone. A wallet utility should not encourage careless copying of payment details.
The free price makes trying it easy, but the app includes in-app purchases ranging from $0.99 to $99.99 per item. That wide range is worth noticing before making a purchase. I would explore the free experience first and only pay for an option if I clearly understood what it adds to my own workflow. Someone who only needs occasional card identification may not get enough value from spending heavily on extras.
The current version is 3.0.5, and the minimum requirement is Android 7.0. That makes it accessible to many Android users, although the practical NFC experience will still depend on the individual phone’s hardware and software behavior. I would check that NFC is available and enabled before assuming the scanning function will be useful on a particular device.
One subtle weakness is the risk of overconfidence. A clean-looking result can feel more official than it really is. I would never use the app to approve a suspicious transaction, verify a stranger’s identity, or decide that a card is authentic without contacting the issuer. Its best role is preliminary checking, not final judgment.
Small workflows that make it more useful
My first tip is to use it during card organization rather than only when a problem appears. If I have several cards, identifying them once and keeping their purpose clear can prevent rushed mistakes later. This is especially useful before travel, online shopping, or moving cards between physical wallets.
My second tip is to separate identification from payment. I would use the BIN and NFC tools to understand which card I am holding, then complete the payment through the bank’s approved channel or the mobile wallet I already trust. This two-step approach takes a little longer than treating the app as an all-purpose payment solution, but it keeps the app’s role clear and reduces the chance of relying on the wrong tool.
My third tip is to use the opening digits as a cross-check, not as a label for the entire account. If the result does not match what I expect, I would stop and compare the physical card, the bank app, and the issuer’s support information. That simple habit turns the validator into a useful warning system without giving it more authority than it deserves.
For people who handle cards for a family member or a small business, I would also recommend minimizing exposure. Do not photograph full card details just to remember which card is which. If a note is necessary, use a short personal label and keep it separate from sensitive numbers. The app can help with recognition without becoming a reason to create a new collection of risky records.
Who will gain the most from it?
I think this app is a good match for users who carry multiple cards and want a quick way to identify them. It also suits people who regularly check card ranges, organize payment instruments, or want an NFC-based inspection option in the same finance utility. The Everyone age rating makes it broadly approachable, though responsible handling of financial information still matters for every age group.
It may also help someone who is learning how payment cards are structured. Seeing how the opening digits relate to card identification can make an otherwise confusing number sequence easier to understand. That educational value is modest, but it is a useful side effect of a focused tool.
I would skip it if my only goal is checking a balance, paying a bill, transferring money, or freezing a card. The official banking app is the more appropriate and authoritative option for those tasks. I would also skip it if I rarely handle more than one card and have no interest in NFC scanning or BIN information; in that case, adding another finance app may create more clutter than convenience.
Likewise, users who expect a complete replacement for Google’s or a bank’s payment system may be disappointed. The app’s identity is narrower. Its value comes from card inspection and organization, not from promising to manage every financial activity on a phone.
My final take
After looking at the way its central tools fit together, I see Credit Card : Wallet & NFC as a specialized utility with a clear practical niche. The BIN validator is the feature that gives it a reason to exist, while NFC scanning makes the process faster when the phone and card cooperate. Together, they can make card sorting and preliminary checking less tedious.
I would recommend trying the free version to anyone who frequently mixes up cards or wants a convenient way to inspect card identifiers. I would not recommend treating it as a banking replacement, a fraud detector, or proof that a payment will succeed. Used with those boundaries in mind, it is a handy addition to an Android finance toolkit rather than an unnecessary imitation of a full mobile wallet.
Galaxy studio apps has positioned the product around a narrow but understandable need, and the strong user response reflects that usefulness. My advice is simple: test the scanner with a card you own, see whether the BIN information fits your routine, and keep sensitive details protected. If that workflow saves you repeated manual checking, the app earns its place; if you only need ordinary banking functions, your existing bank or payment app remains the better choice.
Pros
- Stores multiple cards and passes in one convenient digital wallet.
- NFC payments are quick at compatible contactless terminals.
- Clean interface makes adding and viewing cards straightforward.
- Useful transaction overview helps monitor recent spending activity.
- Can reduce the need to carry a physical wallet every day.
Cons
- NFC payments depend on phone compatibility and supported terminals.
- Some features may require permissions that privacy-conscious users dislike.
- Not all banks, cards, or regions may be supported equally.
- A lost or uncharged phone can prevent access to stored payment options.
- Security depends heavily on device lock settings and account protection.
FAQs for Credit Card : Wallet & NFC
What is Credit Card: Wallet & NFC, and what can I use it for?
Credit Card: Wallet & NFC is a mobile wallet-style application designed to help users organize payment card information and access NFC-related features from a smartphone. Depending on your device, region, and supported services, it may let you store card details, review wallet information, or interact with compatible contactless functions. It should not automatically be assumed to replace your bank’s official app or a certified payment service.
Can I use Credit Card: Wallet & NFC to make contactless payments in stores?
Contactless payment availability depends on your phone’s NFC hardware, operating-system version, country, card issuer, and the payment networks supported by the app. Installing the application alone does not guarantee that your card can be used at a payment terminal. Before relying on it for purchases, check whether your bank and card are supported, enable NFC in system settings, and complete any required verification or security setup.
Is it safe to add my credit card information to the app?
You should treat any wallet application as a sensitive financial tool and review its privacy policy, permissions, developer information, and security options before entering card details. Avoid sharing your PIN, online-banking password, or one-time verification codes inside an unfamiliar app. Use a screen lock, install the app only from an official store, keep your phone updated, and contact your card issuer if you notice suspicious activity.
Does the app connect directly to my bank or replace my banking application?
Credit Card: Wallet & NFC may provide wallet or NFC-related functions, but it should not be considered a full replacement for your bank’s official mobile application unless your bank explicitly confirms compatibility. Account balances, transaction history, card controls, fraud reporting, and card activation are normally managed through the issuer. Always verify important information in your bank’s official app or website rather than relying solely on a third-party wallet.
What should I check before downloading and using Credit Card: Wallet & NFC?
Before downloading, confirm that the application is compatible with your Android or iOS device and that NFC features are supported on your specific model. Read recent reviews, check the listed developer, examine requested permissions, and verify whether the app is available in your country. Also review possible advertisements, in-app purchases, privacy practices, and supported card providers so you understand its limitations before adding financial information.

Credit Card : Wallet & NFC
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support.creditcard@galaxystudioapps.me, visit https://galaxystudioapps.me/creditcard, or review their https://galaxystudioapps.me/creditcard/privacy/.










